
Choosing a City to Invest in Real Estate in India: 2026 Guide
SUYUG Infraupdated
Long guide · 3,370 words · 15 min read · 6 questions answered
Best City to Invest in Real Estate in India as an NRI: 2026 Rankings
India’s residential real estate market in 2026 is not a single story. Total equity capital inflows across the sector hit an all-time high of USD 14.3 billion in 2025 per CBRE data, led heavily by land acquisitions and core commercial assets. The premium segment, projects priced above INR 1 crore, now accounts for the majority of total residential sales, up sharply on the previous year, per JLL’s premiumisation report. And a run of repo rate reductions has meaningfully improved home loan affordability for NRI buyers — we do not print the benchmark, because the Reserve Bank of India revises it by policy decision and publishes the current figure itself; check rbi.org.in, and check what your lender is actually passing through, which is a separate question.
What the aggregate data doesn’t show is how differently these tailwinds play out across cities. The best place to invest in real estate in India for an NRI in Dubai is not necessarily the same as for one in Toronto or London, the yield requirement, currency frame, management friction, and exit liquidity all vary. This guide compares the four most serious NRI investment cities: Bangalore, Hyderabad, Pune, and Mumbai Metropolitan Region, on the criteria that determine actual after-tax, after-management returns for remote investors.
TL;DR
- Bangalore has the deepest GCC-driven employment base of the four, spread across three distinct zones rather than concentrated in one — which is what holds up tenant demand and, with it, the case for the city. This guide compares the four on that and on the other structural axes without publishing yield or appreciation percentages; the figures in circulation are estimates rather than transaction records
- Hyderabad has appreciated strongly, but rental yields lag Bangalore; Telangana Real Estate Regulatory Authority (TGRERA) compliance is strong, but the city’s corporate leasing base is more concentrated
- Pune offers stable mid-market yields and a diversified IT-manufacturing employment base, but has appreciated more moderately, and the premium segment is thinner
- Mumbai Metropolitan Region is India’s most resilient long-term wealth store, but entry prices compress yields significantly; it suits capital preservation more than yield generation
- For NRI investors across all markets, real estate investment in India is strongest in corridors where employment diversity, confirmed infrastructure catalysts, and premium segment supply depth coincide: a combination that Bangalore’s eastern IT belt currently leads
The 2026 Framework: What NRI Investors Should Evaluate
Most city ranking guides use a single metric, usually appreciation rate or rental yield, to arrive at their conclusions. For NRI investors managing a cross-border asset, the relevant evaluation framework is broader.
Five criteria that matter for NRI city selection:
Employment diversity: A city’s rental yield stability depends on the depth and diversity of its corporate tenant base. A corridor anchored by a single employer or sector carries vacancy risk that a multi-employer, multi-sector base does not.
How much of the infrastructure is already delivered: a metro line that is running and a metro line that is approved are different propositions, and the difference is years. Establish, for each city, which programmes are commissioned, which are under construction, and which are still approvals — from the agency executing them, not from a property page. Announced infrastructure carries a timeline risk you do not control; delivered infrastructure does not.
Premium segment depth: NRI buyers typically target the 3-BHK and 4-BHK premium segment. A city needs sufficient premium supply from credible developers to offer genuine choice, and sufficient premium demand from high-income corporate tenants to keep vacancy low.
Remote management friction: From abroad, a property in a well-managed premium gated community in a mature IT corridor is easier to manage than an independent house in a developing sub-market. City selection affects management complexity before project selection does.
Legal and regulatory clarity: RERA compliance, Khata classification, title chain integrity, and DC conversion status vary by city and within corridors. Cities with stronger RERA enforcement and more transparent municipal records reduce the due diligence burden for remote buyers.
The Multi-City Comparison
The table compares the four cities on the axes that hold between quarters, and on where to go to check the ones that do not. It carries no rates, yields or appreciation percentages: those move, and a number left on a page goes on being read as current long after it stops being true. Where a row states a position rather than a source, it is a description of what is on the ground, not a measurement of return.
| Criterion | Bangalore | Hyderabad | Pune | Mumbai MMR |
|---|---|---|---|---|
| Where the price record is public | Kaveri Online Services (Karnataka registration department) | Telangana registration department’s portal | Maharashtra registration department’s record | Maharashtra registration department’s record |
| Who sets the rent | Salaried IT and GCC staff across three zones | IT and pharmaceutical employees, more concentrated | IT, manufacturing, and a large student and young-professional base | Finance and BFSI employees; deepest resale market |
| Principal premium corridors | Sarjapur Road, Whitefield, the ORR belt | Kokapet, Gachibowli | Kharadi, Hinjewadi | Worli, Bandra, Lower Parel, selected Thane micro-markets |
| GCC and IT employment depth | Very high, 3 distinct zones | High, Hyderabad Pharma City + IT | Moderate, IT + manufacturing | High, finance + BFSI |
| Premium supply depth | High | Moderate-High | Moderate | High, concentrated in prime micro-markets |
| Infrastructure pipeline | Metro Phase 3A, PRR, SWIFT City | ORR Phase 2, Pharma City SEZ | Metro Line 3, Ring Road | Trans Harbour Link, Metro |
| RERA enforcement | Strong, K-RERA | Strong, TG-RERA | Strong, MahaRERA | Strong, MahaRERA |
| Remote management friction | Low, mature gated community stock | Low-Moderate | Moderate | Low in premium segments |
| NRI entry price in USD | Convert the rupee entry at the RBI reference rate on your remittance date | As above | As above | As above |
Bangalore: The High-Yield, High-Appreciation Case
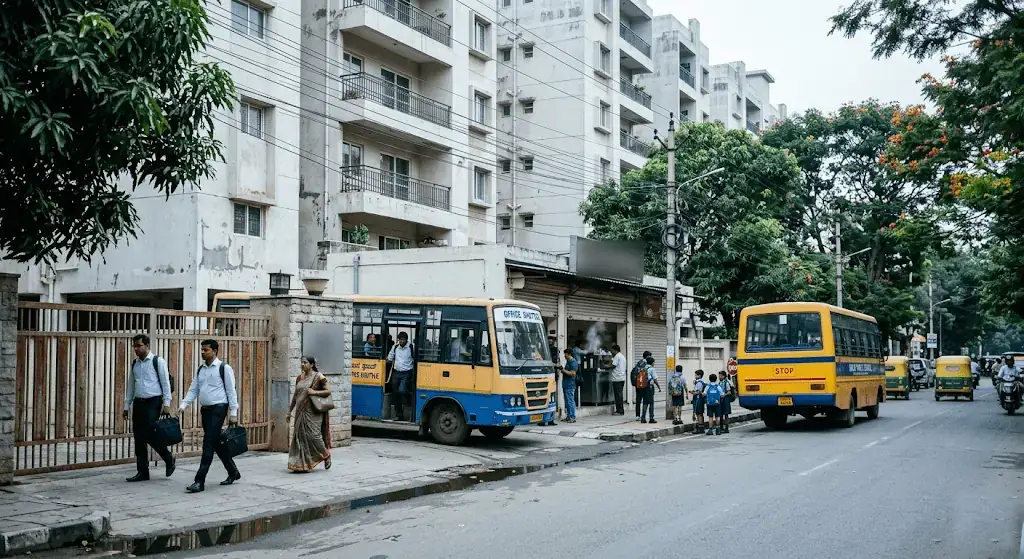
Bangalore’s position as the best city to invest in real estate in India for yield-focused NRI investors rests on a structural argument, not just a data point.
The GCC and IT employment thesis:
Global Capability Centres accounted for close to two fifths of total office leasing in Bangalore in 2025, with most of that demand originating from North American firms, per Knight Frank. That creates a rental tenant pool of senior IT professionals with low default risk, long average tenancy, and the capacity to absorb an annual escalation — the three things that matter to a landlord who cannot fly in to chase a payment.
JLL’s Q1 2026 residential data shows Bangalore recording over 18,000 unit sales in a single quarter, with developers heavily concentrating on the premium segment above INR 1.5 crore, which took the majority of quarterly new launches. This is not speculative demand, it is corporate employment driving residential absorption at scale.
The Sarjapur Road case within Bangalore:
Sarjapur Road repriced harder than any other Bangalore corridor between 2021 and 2024. We do not attach a percentage to that: the figures quoted for the corridor are estimates of listing rates rather than records of what anyone paid. The version you can check is on the public record — registered sale considerations for the same survey number at two dates, from Kaveri Online Services.
Within the corridor, the zones toward Carmelaram and Bellandur sit at the top on both price and rent, and are the most built out. Mid-corridor entry at Sompura Gate sits below them, and it is also where the announced infrastructure has furthest still to travel: Metro Phase 3A (Hebbal–Sarjapur, a 36.59 km route in the DPR the state cabinet cleared; no sanctioned cost, because the Union government has not approved it), the Peripheral Ring Road Phase 1, and SWIFT City (1,000-acre KIADB startup complex) are all confirmed on paper and none of them delivered.
Where Bangalore’s risk lies:
Water supply infrastructure across peripheral sub-zones remains incomplete despite Cauvery Stage 5 commissioning. Buyers must verify BWSSB feasibility certificates per project. Traffic congestion on the Iblur-ORR junction and Kasavanahalli connector roads is real and affects commuting. Neither risk eliminates the investment thesis, but both require project-level due diligence.
Hyderabad: Strong Appreciation, Maturing Yield Profile
Hyderabad’s growth story over the past five years is genuine. The Kokapet and Gachibowli corridors repriced substantially between 2021 and 2024, driven by Hyderabad’s emergence as a major IT and pharmaceutical hub. As with Bangalore, we publish no percentage: check it against registered transactions in the relevant survey numbers on the Telangana registration department’s portal before treating any quoted figure as fact.
The case for Hyderabad:
Entry costs in the premium West Hyderabad corridors are no longer obviously below Bangalore’s for comparable configurations — check both against the two states’ registration records before assuming otherwise. What the city does have is substantial infrastructure investment (Outer Ring Road Phase 2, Pharma City SEZ) and a RERA framework under TG-RERA that has improved developer accountability. Land availability and the state government’s pro-development stance have sustained a premium project pipeline.
Where Hyderabad lags for NRI investors specifically:
The corporate leasing base, while growing, is more concentrated in pharmaceuticals and IT than Bangalore’s multi-sector GCC depth — which means a smaller number of employers stand behind the rent, and vacancy risk is less spread. We publish no yield comparison between the two cities; compute each from live listings in the sub-zone you are considering. But for a buyer whose return depends materially on rental income rather than on holding the asset, concentration of the tenant base is the risk to weigh.
The city also lacks Bangalore’s density of international schools in premium residential corridors; a factor that matters for NRI buyers planning eventual return with school-age children, and for the affluent family-tenant demographic that drives premium yield.
Who Hyderabad suits:
NRI investors with a longer appreciation horizon (7–10 years), lower yield requirement, and willingness to hold through the corridor’s maturation. Land availability permits large, highly standardised mega-gated layouts at a scale Bangalore’s constrained corridors cannot match, which is what makes the long-horizon case here — and whatever leverage your lender extends works harder against a lower entry price.
Pune: Stable Returns, Selective Micro-Markets
Pune’s real estate market is the most stable of the four, which is both its strength and its constraint for growth-oriented NRI investors.
The case for Pune:
The city combines IT employment (Hinjewadi, Kharadi, Viman Nagar) with a significant manufacturing and automotive base, creating broader employment diversity than purely IT-driven corridors. Gross rental yields in established premium micro-markets are consistent rather than high, supported by a large student and young professional population. MahaRERA is among India’s most active state regulators with strong developer compliance enforcement.
Where Pune constrains return:
Pune’s premium segments repriced more moderately over the 2021–2024 period than Bangalore’s or Hyderabad’s. The premium segment is thinner: fewer large-format gated communities with international-standard amenities, and a lower density of the senior IT-professional tenant profile that drives Bangalore’s high yield.
Infrastructure catalysts exist, and the difference from Bangalore is how far along they are: Pune’s Metro Line 3 is close to commercial operation and its Ring Road is already under construction, where Bangalore’s Phase 3A is an approval rather than a running line. Take each date from the executing agency rather than from a property page. Delivered infrastructure is a different proposition from announced infrastructure — steadier, and with less left to wait for.
Who Pune suits:
NRI investors seeking stable, predictable yields with lower volatility and lower management friction risk. Suitable for a secondary allocation within a diversified NRI real estate portfolio rather than as the primary appreciation vehicle.
Mumbai Metropolitan Region: Wealth Preservation at Premium Entry
The Mumbai Metropolitan Region (MMR), covering Mumbai, Thane, Navi Mumbai, and the extended suburbs, is India’s most established residential real estate market, and its most expensive.
The case for MMR:
Mumbai has the deepest liquidity of any Indian residential market. The resale transaction velocity is higher than in any other city, which matters for NRI investors who need exit flexibility. Long-term wealth preservation in prime locations (Worli, Bandra, Lower Parel, select Thane micro-markets) is well-documented. Infrastructure investment is substantial: Trans Harbour Link, Coastal Road, and Metro expansion across multiple lines.
Where MMR constrains NRI yield investors:
Entry costs in premium MMR segments start well above the other three cities for 3-BHK configurations, and rent does not rise in the same proportion — which is the whole of the yield problem. Work it through on the specific unit rather than on a rule of thumb: rent net of the statutory NRI rental TDS withholding and local property management fees, against total acquisition cost including stamp duty and registration. Then run the identical calculation on a Bangalore or Pune unit you would actually buy instead, using each city’s own registered transaction values as the denominator. The comparison that decides this is the one you run, not the one a developer runs for you.
Mumbai also has among the most complex municipal documentation requirements in India: Occupation Certificate issuance, society formation, and stamp duty calculations have historically been more procedurally involved than Karnataka’s framework.
Who MMR suits:
NRI investors prioritise long-term wealth preservation, maximum exit liquidity, and proximity to India’s financial capital for personal use. It’s the best place to invest in real estate in India for capital storage with low yield expectations. Not optimal for yield-maximising NRI portfolio allocation.
The Verdict: Which City for Which Investor Profile
| Investor Profile | Recommended City | Rationale |
|---|---|---|
| Yield-first NRI (rental income priority) | Bangalore — Sarjapur Road | Tenant base spread across three IT employment zones; deepest premium rental stock |
| Appreciation-first NRI (long horizon) | Bangalore or Hyderabad | Both have confirmed infrastructure catalysts; Bangalore has more employment diversity |
| Capital preservation NRI | Mumbai MMR | Deepest liquidity; most established long-term store of value |
| Balanced NRI (yield + appreciation) | Bangalore | Multi-employer tenant demand alongside announced infrastructure still to be delivered |
| First-time NRI investor (lower entry) | Pune or Hyderabad | Pune has lower entry prices, both have stable RERA frameworks, and lower management friction |
For most NRI investors evaluating real estate investment in India as a portfolio allocation in 2026, Bangalore is where the shortlist starts — not because the other cities lack merit, but because it is the one where employment diversity, premium supply depth, a public transaction record and functioning RERA enforcement all sit together, and where the infrastructure being counted on is still ahead rather than behind. Whether being early is an advantage depends on a timeline nobody selling you a flat controls.
Explore Suyug’s K-RERA-registered apartments at Sompura Gate, Sarjapur Road, positioned at the mid-corridor entry point of the Sarjapur Road sub-zone matrix. On green building the two projects are not in the same position and we do not merge them. THE1 holds IGBC pre-certification, a design-stage assessment by the Indian Green Building Council ahead of the final certificate awarded on completion. Saffron is designed to align with IGBC guidelines and has not been assessed. Contact our NRI advisory team to understand how Sarjapur Road fits your 2026 portfolio allocation.
One Thing Worth Sitting With
The best city to invest in real estate in India question is really two questions: best for what, and best for whom. For NRIs whose return depends on rental income over a 5–7 year horizon, Bangalore has the deepest and most diversified tenant base of the four. For those optimising exit liquidity, Mumbai has the deepest resale market. For those wanting a lower entry and infrastructure that is already delivered rather than announced, Pune is a credible alternative. The mistake most NRI investors make is treating city selection as a universal ranking rather than a decision that should follow from their own return requirement, liquidity needs, and holding horizon.
Frequently asked questions
Rent, not appreciation — and the difference is structural rather than numerical. Bangalore’s eastern corridors draw tenants from three distinct IT zones plus GCC demand from North American firms, so vacancy risk is spread across several employers; Hyderabad’s corporate leasing base is more concentrated in IT and pharmaceuticals. We publish no yield percentage for either city. Check it the same way in both: take live listings for the same configuration in the sub-zone you are considering, note how long each has been advertised, and divide the achievable rent by the all-in acquisition cost including stamp duty, registration and GST. Hyderabad remains a legitimate alternative for buyers with longer horizons and lower income requirements.
Mumbai suits NRI investors who are prioritising exit liquidity and long-term capital storage over current income. We publish no entry price and no yield figure for it, but the mechanism is worth understanding before you compare: entry costs in MMR’s premium segments are the highest of the four cities here, and rent does not rise in the same proportion, so the ratio of one to the other is compressed. Run it yourself on a specific unit — achievable rent net of the statutory NRI rental TDS withholding and management fees, over total acquisition cost — and run the same calculation on a Bangalore or Pune equivalent. Mumbai has the deepest resale transaction velocity of the four, which is the argument for it on a 10–15 year horizon.
Three announced programmes: Metro Phase 3A (the Hebbal–Sarjapur corridor, a 36.59 km route in the DPR the state cabinet cleared; no sanctioned cost, because the Union government has not approved it), Peripheral Ring Road Phase 1 (the outer ring alignment, tendering active), and KIADB SWIFT City (1,000-acre startup complex adjacent to Sarjapur Road). All three are confirmed on paper and undelivered on the ground, and each has already slipped once. Their current stage and timeline belong to the bodies executing them — BMRCL for the metro, kiadb.in for SWIFT City — so read them there rather than through a developer. We publish no figure for what a commissioning is worth per square foot; the ones quoted are modelled, not measured. The timeline, not the programme, is the risk you are taking.
All four cities have active RERA frameworks — Karnataka (K-RERA), Telangana (TG-RERA), and Maharashtra (MahaRERA) are among India’s most active state regulators. MahaRERA publishes its own complaint disposal numbers, which are worth reading against the other regulators’ before treating any of them as equivalent. K-RERA covers both Bangalore metros and has a well-functioning online portal for tower-wise project verification. For NRI buyers doing remote due diligence, all four cities offer functional online verification; the differentiator is project-level compliance, not city-level framework.
Not from a band on a page — including this one, which publishes none. Build it in three steps. First, take registered sale considerations for the specific sub-zone from that state’s registration record (Kaveri Online Services for Karnataka; the equivalent registration department portal in Telangana and Maharashtra), because that is what people actually paid rather than what anyone is asking. Second, add the statutory layer: stamp duty and registration at the rates that state has in force, plus GST if the unit is under construction. Third, establish the equity you have to fund, which depends on the loan-to-value your lender approves — set by RBI norms and the lender’s own credit policy, and different for NRI applicants. Ask the lender for its current NRI LTV in writing. Of the four, Pune and Hyderabad sit lowest on entry and Mumbai MMR highest by a wide margin; that ordering is stable, the numbers are not.
Global Capability Centres accounted for over 35% of Bangalore’s office leasing in 2025, with roughly 75% from North American firms, per Knight Frank. Each GCC expansion adds a cohort of salaried senior IT professionals to the corridor, and they are the primary tenant pool for 3 BHK and 4 BHK apartments in places like Sarjapur Road. That cause-and-effect between office leasing and residential rental absorption is the structural reason Bangalore’s tenant demand holds up, and it is the part of the case you can check — the leasing volumes are published quarterly by the consultancies, and the vacancy is visible in how long units sit advertised. The yield itself is yours to compute; we publish none.
Was this useful?
Comments
Was this useful?
Schedule a site visit
Leave your details and the team will call back to fix a convenient date.