Why NRI Real Estate Investment from the Middle East Is Concentrating on Sarjapur Road
SUYUG Infra
Short briefing · 2,629 words · 12 min read · 6 questions answered
In this article · 7 sections
There is a particular logic driving Gulf-based NRI capital toward Indian real estate in 2026 that doesn’t apply in the same way to NRIs in the US or UK. The UAE Dirham is pegged to the US Dollar. The Indian Rupee is not, and has moved against the dollar over nearly every multi-year window. For an NRI holding savings in AED, that difference means rupee-priced property costs less in dirham terms than the rupee price alone suggests — and, on the way out, that a rupee gain arrives in dirhams smaller than it looked.
That currency dynamic, combined with regional geopolitical uncertainty in the Middle East and a maturing premium residential market in Bangalore, has produced a structural shift in how Gulf-based professionals are allocating capital. NRI investment in India real estate from GCC countries has moved from occasional to systematic and from a sentiment-driven connection to a wealth-preservation strategy. NRI real estate decisions that were once deferred indefinitely are now being made with financial precision. And within Bangalore, the capital is concentrating on one corridor more than any other: Sarjapur Road.
TL;DR
- The AED is pegged to the USD and the rupee is not, so rupee movement lands on a dirham buyer at entry and again at exit — cheaper going in, smaller gain coming out. Take the actual move for your own dates from the RBI reference rate; it is a mechanism, not a trend you can bank on
- NRI participation in Indian residential transactions has risen over the past decade, with GCC buyers prominent among them. The percentages in circulation are industry estimates rather than a published registration statistic, so we quote none
- Sarjapur Road is among the Bangalore corridors that repriced hardest between 2021 and 2024; we publish no percentage for it, because the figures in circulation are estimates rather than registered transaction records
- Luxury apartments in Sarjapur Road earn their rent from the corridor’s school ecosystem and employment density, which is what makes the demand durable — the yield itself you should compute from live rents for the same configuration nearby, not from a published band
- Ready-to-move-in assets eliminate the execution risk that most concerns remote Gulf buyers, with no construction delays, no remote furnishing coordination, immediate rental income
The Dirham-Rupee Advantage: Why Gulf NRIs Have Structural Purchasing Power
The currency arithmetic is the starting point for any Gulf NRI considering Indian real estate. The UAE Dirham is pegged to the US Dollar at a fixed rate of approximately AED 3.67 per USD. The Indian Rupee carries no such peg, and has moved against the dollar over nearly every multi-year window.
What this means in practice:
Run the conversion at both ends of your holding period rather than at one. A rupee price converted into dirhams today, and the same asset’s rupee price converted into dirhams at exit, will not show the same gain the rupee figure shows — the currency takes part of it. This cuts both ways and it is the whole of the dirham buyer’s structural position: entry is cheaper than the rupee price implies, and the exit gain is smaller than the rupee gain implies. Anyone presenting only the first half is selling. Take both conversions from the RBI reference rate for your actual dates.
The same arithmetic is what undermines the default alternative. NRE fixed deposits are contracted at the bank’s prevailing rate — take it from the bank’s own NRE rate card, not from a page like this one — but they are held in rupees, so the currency erodes the return over the term while home-country tax, where it applies, takes another slice. Over a long deposit the real AED-denominated return can approach zero. Physical property in an occupied corridor at least holds a real asset against that drag; a deposit holds nothing but the rupee.
The Gulf Capital Shift: What’s Driving NRI Investment Back to India
The surge in foreign investment in real estate in India from GCC countries isn’t random. Several structural factors have converged to make 2025–2026 a particularly active period for Gulf NRI property acquisition.
Geopolitical wealth preservation
Regional instability in the Middle East has heightened income and job uncertainty among Indian expatriates, many of whom work in sectors directly exposed to oil price cycles and geopolitical risk. Building an asset base in India — specifically a residential apartment in a corridor with occupational demand that does not depend on one employer — has become a priority for professionals who previously deferred the decision indefinitely.
The retirement anchor
Several million Indians live and work in GCC countries, the great majority on employment visas with no permanent residency pathway. Retirement means returning to India, and the question of where to live and what financial foundation to return to becomes pressing for professionals in their forties and fifties. A premium apartment in Bangalore’s IT corridor, generating rental income in the interim and ready for personal use upon return, addresses both the investment and the lifestyle requirements simultaneously.
The eldercare driver
Many Gulf-based NRIs maintain aging parents in India. Securing a premium, well-managed apartment in a gated community with healthcare proximity rather than leaving parents in a family home that requires active management is an increasingly common motivation for property purchase in corridors like Sarjapur Road.
Why Bangalore, and Specifically Sarjapur Road
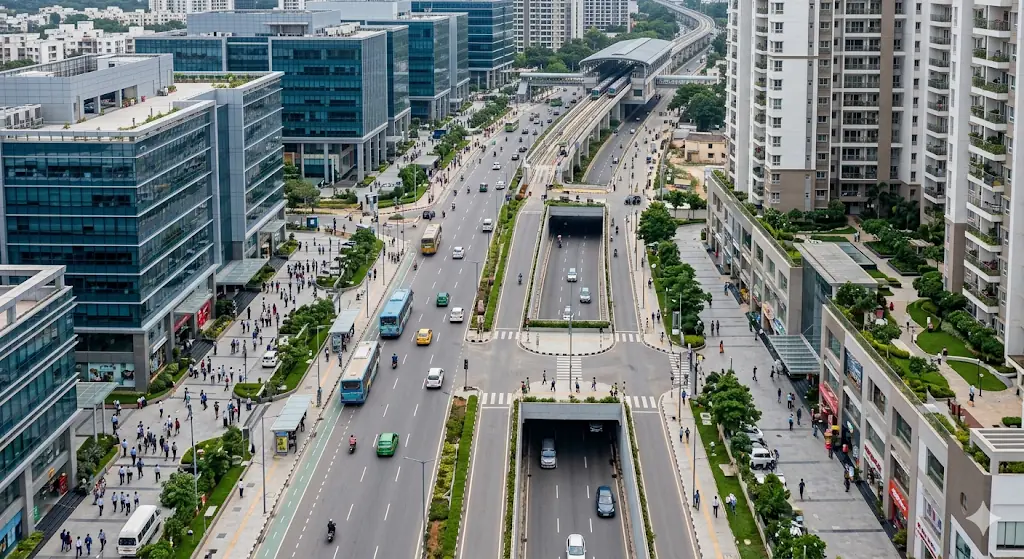
Among India’s tier-1 cities, Bangalore leads NRI real estate investment from the Gulf for reasons that go beyond sentiment. The city’s IT employment base — and specifically its Global Capability Centre cluster, whose office leasing volumes the international property consultancies report quarterly — creates a structural rental tenant pool that Dubai-based investors understand instinctively: the same companies employing colleagues in Gulf tech parks are headquartered in Bangalore’s ORR corridor.
For Gulf-based professionals evaluating NRI investment in India real estate, the two things about Bangalore that can be checked rather than asserted are its corporate office leasing volumes, reported quarterly by the international property consultancies, and the density of international schools in its eastern corridors, which you can count.
Within Bangalore, Sarjapur Road draws a disproportionate share of Gulf NRI enquiry in 2026, for three specific reasons:
Employment gravity
The corridor sits at the intersection of three major IT employment zones of Wipro’s corporate campus at Sompura Gate, the ORR tech belt (RMZ Ecoworld, Ecospace, Embassy Tech Village), and Electronic City via Dommasandra. Multi-employer demand means rental occupancy doesn’t depend on a single company’s hiring decisions.
School ecosystem
Oakridge International, Indus International, Greenwood High, TISB, and NPS East together create one of the densest international school concentrations in India. For Gulf NRI families planning eventual return, the ability to transition children into IB, IGCSE, or CBSE programmes without compromising on school quality is a meaningful pull factor.
Appreciation trajectory
Sarjapur Road repriced substantially between 2021 and 2024. We deliberately do not attach a percentage to that sentence: the figures quoted for the corridor come from estimates of listing rates, not from what anyone paid, and they are quoted far more often than they are sourced. The version you can verify is on the public record — pull registered sale considerations for the same survey number at two dates from Kaveri Online Services and compute it yourself, then convert both ends into dirhams. The infrastructure pipeline (Metro Phase 3A, PRR, SWIFT City) is the reason to think a further cycle is ahead; it is not a promise that one is.
The Sarjapur Road Investment Case: Yield, Appreciation, and Infrastructure
For Gulf NRIs evaluating luxury apartments in Sarjapur Road as an investment, the structure of the corridor is what tells the story. The numbers are yours to build.
How the sub-zones differ:
| Sub-Zone | Position on the corridor | Primary Tenant | What that means for a remote landlord |
|---|---|---|---|
| Carmelaram–Bellandur | Priciest; nearest the ORR | Senior IT executives | Shortest vacancy gaps; the infrastructure here is already built |
| Kasavanahalli | Mid; established | Double-income families | Longer tenancies, slower turnover, school-cycle timing |
| Sompura Gate | Entry point of the three | Tech professionals; school proximity | Lowest entry, longest wait on infrastructure |
To size the income in dirhams: take the achievable monthly rent from live listings for the same configuration in completed projects nearby (and discount them, because listings are asks), deduct maintenance, property tax and a vacancy allowance, then convert at the RBI reference rate. What the peg gives you is not a bigger number — it is a stable one, since income arriving in a dollar-anchored currency does not move with the dirham.
The infrastructure pipeline
Metro Phase 3A (the Hebbal–Sarjapur corridor, 28 stations), the Peripheral Ring Road Phase 1 (tendering began 2026), and the 1,000-acre KIADB SWIFT City development are the announced programmes on the corridor. Their timelines belong to the bodies executing them — BMRCL for the metro, kiadb.in for SWIFT City — and we do not restate them here. Each is confirmed on paper and undelivered on the ground, and each has slipped before. Treat them as the reason the mid-corridor is priced where it is, not as a schedule you can plan an exit around.
The Ready-to-Move Imperative: Why Remote Buyers Should Avoid Under-Construction
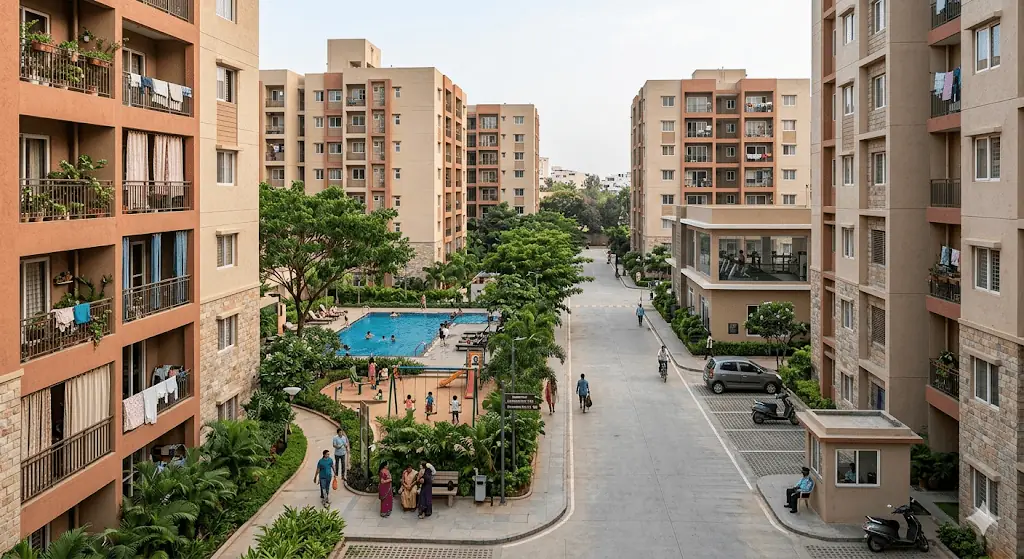
For Gulf-based NRIs specifically, the under-construction vs. ready-to-move decision is not a matter of preference but a risk management question. It is also increasingly the defining factor in how serious NRI real estate buyers from the GCC approach the Sarjapur Road market.
The remote execution problem:
Under-construction projects require active monitoring with site visits, construction progress verification, and quality checks at key stages. A buyer in Dubai cannot do this easily. The developer’s construction updates are not an independent audit. And if possession slips by a year or more — check the developer’s own delay notices and complaint record on K-RERA before assuming it will not — the carrying cost of an untenanted asset adds up materially.
The furnishing problem:
Most under-construction apartments are handed over as warm shells: with flooring, painting, sanitary fittings, and countertops fitted in. However, the rest becomes a second project for an NRI buyer: coordinating interior design, procurement, and installation from abroad. We publish no figure for what that costs, because it depends entirely on the handover specification and on what you choose to put in. Get written quotes from two Bangalore contractors against the developer’s handover specification, and add the months it takes before the apartment can be let.
The ready-to-move advantage:
A ready-to-move, RERA-cleared apartment allows the buyer to verify what they’re actually getting before any money changes hands beyond booking. OC is obtained. The structure is complete. For furnished or semi-furnished options, rental income begins immediately, eliminating the empty-property holding cost that compounds across delayed under-construction timelines.
The Legal Framework: What Gulf NRIs Need to Know
NRI real estate transactions in India are governed by a clear regulatory framework under FEMA and RBI guidelines. Here is what Gulf NRIs need to know before proceeding.
Eligibility: NRIs, OCIs, and PIOs can purchase residential and commercial property in India freely under FEMA. Agricultural land, farmhouses, and plantations are prohibited.
Fund routing: All payments must flow through NRE, NRO, or FCNR accounts. Direct transfers from overseas accounts to developers are not FEMA-compliant and compromise repatriation rights at exit.
Remote execution: A transaction-specific Power of Attorney, attested at the Indian diplomatic mission in the UAE (or relevant GCC country) and adjudicated at the Indian Sub-Registrar’s office, allows complete remote execution.
Repatriation: Sale proceeds from properties purchased with NRE/FCNR funds are fully repatriable. Properties purchased through NRO funds are repatriable up to USD 1 million per financial year after applicable taxes.
Tax: Rental income is subject to Indian income tax with a standard 30% deduction for maintenance. TDS of 31.2% is deducted by tenants on NRI landlord income. LTCG on sale is 12.5% flat for properties held over 24 months. The India-UAE DTAA provides relief against double taxation.
Suyug is fully RERA registered and provides complete legal support for NRI buyers — from POA setup and title verification to banking compliance and post-purchase management. Contact Suyug’s NRI advisory team to explore Saffron, Sarjapur Road.
One Thing Worth Sitting With
The Gulf NRI’s case for Sarjapur Road is not built on sentiment. It is built on a currency mechanism that cuts both ways and should be run at both ends, a rental market anchored to three separate employment zones rather than one, and an infrastructure pipeline that is announced and undelivered.
For NRI investment in India real estate from the Gulf, what makes luxury apartments in Sarjapur Road worth the work is that the important parts of the claim can be checked before you book: the RERA registration tower by tower, the density by dividing units by acres from that same registration, and each infrastructure programme’s status from the body executing it. The part nobody can check for you is the timeline — and that is the risk you are actually taking.
Frequently asked questions
The UAE Dirham is pegged to the US Dollar; the Indian Rupee is not, and has moved against the dollar over nearly every multi-year window. That difference, not any forecast, is the mechanism: rupee-priced property costs a dirham buyer less than the rupee price alone suggests, and a rupee gain arrives in dirhams smaller than it looked. Take the actual move over your own holding window from the RBI reference rate rather than an assumed annual rate from any brochure, including ours.
Yes, via a transaction-specific Power of Attorney attested at the Indian diplomatic mission in the UAE (or relevant GCC country) and adjudicated at the Indian Sub-Registrar’s office. The POA holder executes registration on your behalf. Suyug’s NRI advisory team manages the full process remotely: title verification, RERA compliance, banking setup, and post-possession management.
Tenants are required to deduct TDS at 31.2% on rental payments to NRI landlords. A standard 30% deduction is available on gross rent for maintenance and repairs before computing taxable income.
Under-construction projects require active construction monitoring, which is impractical from abroad, and they add a second project after handover: interior fit-out procured and installed from another country before the unit can be let. We publish no cost figure for that — it depends on what the developer hands over and what you specify — so get written quotes from two Bangalore contractors against the handover specification before you commit. Ready-to-move assets allow verification before purchase, remove delivery risk, can be let from handover, and avoid the holding cost of an empty unit during a delayed construction timeline.
Properties purchased with NRE or FCNR funds: sale proceeds fully repatriable after applicable Indian taxes. Properties purchased through NRO funds: repatriation capped at USD 1 million per financial year post-tax. Repatriation is processed through your NRE or NRO account via normal banking channels, and no special RBI approval is needed for residential property transactions within these limits.
The corridor combines employment diversity (Wipro’s campus, the ORR tech belt, and Electronic City), creating rental demand independent of any single employer; one of Bangalore’s densest international school ecosystems for returning families; and three announced infrastructure programmes (Metro Phase 3A, PRR, SWIFT City), none of them operational and each with an executing body that publishes its own status. We do not publish an appreciation percentage for the corridor: the figures in circulation are estimates rather than transaction records, and a Gulf buyer sizing a 5–7 year horizon should build the number from registered sale considerations on Kaveri Online Services instead.
Was this useful?
Comments
Was this useful?
Schedule a site visit
Leave your details and the team will call back to fix a convenient date.